DLF known for its controversial IPO where small investors were looted is facing irk from professional Investment Research firm based out of Canada and very well known for its unbiased and bold SELL Reports due to bad management practices.
Veritas does not believe in the the disclosed book equity and asset base of the Company. DLF via its dealings with DLF Assets Ltd, from FY07 to FY11, the Company inflated sales by at least INR 11,236 Cr and its profit before tax (PBT) by INR 7,233 Cr. DLF has undertaken questionable related party transactions to boost the value of DAL prior to its acquisition by DLF, thereby subverting the interest of minority shareholders via a higher purchase price for DAL.
Fake Promises of DLF Management:
JV with Hilton has ended and Silverlink Resorts is up for sale
build mega townships (exited Bidadi in Karnatka and Dankuni in West Bengal)
build a mega convention center in the NCR region (exited in 2009)
None of the above have materialized.
Veritas finally concludes the report with a best case valuation of DLF is worth INR 100/share - less than half its current stock price of INR 226.9.
Ministry of Corporate Affairs Orders Inquiry: The MCA has ordered an inquiry to Audit the Books of Accounts of DLF after it has received complaints from Investors.
Friday, March 02, 2012

Tuesday, February 28, 2012
Price List of Various Sobha Developers Projects
Here is Price List of Various Projects of Sobha Developers in Bangalore / Bengaluru, Chennai and Pune.
Price List of Sobha Developers Projects in Bangalore
Bangalore Sobha City - Phase II Near Hebbal flyover - 4500 / sft
Bangalore Sobha Pristine Belandur, ORR Residential apartments 4500 / sft
Bangalore Sobha City - Phase I Near Hebbal flyover Mixed-use residential 4500
Bangalore Sobha Signature Off Sarjapur Road Residential apartments 4500
Bangalore Sobha Forestview Kanakpura Road Residential apartments 4500
Bangalore Sobha Habitech Hopefarms, Whitefiled Residential apartment 4750
Bangalore Hosakerehalli Property Hosakerehalli, Mysore road Residential apartments 3500
Bangalore Sobha Tranquility Hosahalli, Kanakpura Road Residential apartments 3500
Bangalore Sobha Gladiola Thalaghattapura, Kanakpura Road Residential apartments 3500
Bangalore Dairy Circle Property Bannerghatta road Mixed use residentia 4000
Bangalore City Property Minerva Mills, Gopalapura Mixed-use residential 8000
Price List of Sobha Developers Projects in Chennai
Chennai Sobha Serene Seneerkuppam, Porur Residential apartments 4500
Chennai Sobha Meritta Pudupakkam Residential apartments 4500
Price List of Sobha Developers Projects in Pune
Pune Sobha Garnet NIBM Kondwa 3900
Pune Sobha Ivory NIBM, Kondhwa 3500
Pune Thergaon property Thergaon 3000
Price List of Sobha Developers Projects in Bangalore
Bangalore Sobha City - Phase II Near Hebbal flyover - 4500 / sft
Bangalore Sobha Pristine Belandur, ORR Residential apartments 4500 / sft
Bangalore Sobha City - Phase I Near Hebbal flyover Mixed-use residential 4500
Bangalore Sobha Signature Off Sarjapur Road Residential apartments 4500
Bangalore Sobha Forestview Kanakpura Road Residential apartments 4500
Bangalore Sobha Habitech Hopefarms, Whitefiled Residential apartment 4750
Bangalore Hosakerehalli Property Hosakerehalli, Mysore road Residential apartments 3500
Bangalore Sobha Tranquility Hosahalli, Kanakpura Road Residential apartments 3500
Bangalore Sobha Gladiola Thalaghattapura, Kanakpura Road Residential apartments 3500
Bangalore Dairy Circle Property Bannerghatta road Mixed use residentia 4000
Bangalore City Property Minerva Mills, Gopalapura Mixed-use residential 8000
Price List of Sobha Developers Projects in Chennai
Chennai Sobha Serene Seneerkuppam, Porur Residential apartments 4500
Chennai Sobha Meritta Pudupakkam Residential apartments 4500
Price List of Sobha Developers Projects in Pune
Pune Sobha Garnet NIBM Kondwa 3900
Pune Sobha Ivory NIBM, Kondhwa 3500
Pune Thergaon property Thergaon 3000
Monday, February 27, 2012
Bangalore Strong Commercial Today = Residential Tomorrow
Bengaluru absorbed 11.7 mn sq ft of commercial space in CY2011, 33% of the overall absorption of India’s top seven cities. Bengaluru outperformed as it is
an IT hub and IT/ITES absorbed 35% of the commercial space across the top seven Indian cities. Bengaluru is likely to add 22-23 mn sq. ft of commercial space over CY2012-14, implying demand will outpace supply, leading to lower vacancies and rising rentals.
Strong demand for commercial space augurs well for residential volumes in the coming years. In CY2011, Bengaluru created 0.12 mn (assuming 100 sq ft of space per person) future customers for residential space, who can potentially consume 70 mn sq ft (1,200 sq ft per person assuming 50% will buy) of residential space.
Residential sales have been steady in Bengaluru at 4mn sq ft/month in CY2011, which is 20% of total sales in India’s top seven cities.
an IT hub and IT/ITES absorbed 35% of the commercial space across the top seven Indian cities. Bengaluru is likely to add 22-23 mn sq. ft of commercial space over CY2012-14, implying demand will outpace supply, leading to lower vacancies and rising rentals.
Strong demand for commercial space augurs well for residential volumes in the coming years. In CY2011, Bengaluru created 0.12 mn (assuming 100 sq ft of space per person) future customers for residential space, who can potentially consume 70 mn sq ft (1,200 sq ft per person assuming 50% will buy) of residential space.
Residential sales have been steady in Bengaluru at 4mn sq ft/month in CY2011, which is 20% of total sales in India’s top seven cities.
Wednesday, February 15, 2012
Delhi NCR - 4 Year Property Price Trends
The Following Chart shows the price trends of Average Residential Apartment Prices in Delhi NCR - Noida, Gurgaon, Faridabad, Ghaziabad and Greater Noida between 2007 and 2011.

Data Source - Goldman Sachs Property Research.
Do you think this is in-line with the National Housing Index ?

Data Source - Goldman Sachs Property Research.
Do you think this is in-line with the National Housing Index ?
Tuesday, February 14, 2012
4 Years Property Price - Chennai Vs Bangalore Vs Hyderabad
The following Chart Shows the Movement and Comparison of Average Residential Apartment Prices in Chennai Vs Bangalore Vs Hyderabad in Rs / SFT
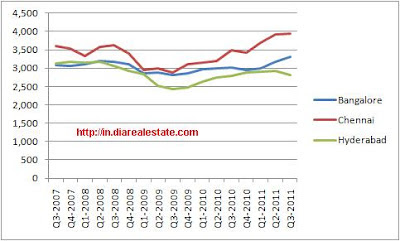
This is for Average Residential Apartments and excludes High End or Luxury Apartments.
Data Source : Glodman Sachs Properties Report.

This is for Average Residential Apartments and excludes High End or Luxury Apartments.
Data Source : Glodman Sachs Properties Report.
Monday, February 13, 2012
Last 4 Years Bangalore Property Price Vs Sales - Analysis
We would like to share with our readers Home / Apartment Prices Vs Sales in Bangalore in the last 4 years 2007 to 2011. Doesn't include Luxury Apartments. The Average ones that are being sold for the Middle Class is the focus of our study.
In the Chart Below
Maroon Line - Average Property / Apartment Price / SFT LHS
Blue Line - Sales in Mn SFT / RHS
 As evident from the Graph above, Bangaloreans / Bengalurueans made their Home Purchases in-line with the Rising Property Prices. Except in Q2/Q3 2009 when the property prices bottomed out, over 7.5 Mn SFT of apartments were absorbed and now when the prices have hit an all time High of Rs 3300 / SFT, Sales has also shot up. The herd mentality of Software Engineers ;-)
In the Chart Below
Maroon Line - Average Property / Apartment Price / SFT LHS
Blue Line - Sales in Mn SFT / RHS
 As evident from the Graph above, Bangaloreans / Bengalurueans made their Home Purchases in-line with the Rising Property Prices. Except in Q2/Q3 2009 when the property prices bottomed out, over 7.5 Mn SFT of apartments were absorbed and now when the prices have hit an all time High of Rs 3300 / SFT, Sales has also shot up. The herd mentality of Software Engineers ;-)
Monday, January 23, 2012
Price correction eminent in Mumbai Property Market
Mumbai residential prices registered CAGR of 14.6% over the last 8 years. Anecdotal analysis shows CAGR growth of 9-10% over the last 2-3 decades. We believe the unprecedented growth in Mumbai prices is not sustainable and will undergo mean revision over the next 1-2 years.
Ears on the Ground and site-visits verified availability of discounts up to 5-7% depending on the project. Developers have launched promotions such as absorption of pre-EMI interest till delivery, floor rise waivers, partly furnished apartments to attract customers. Significant discounts are only available to those who are ready to make advance payments. We continue to believe developers will oblige with further discounts (15-25%) as volumes continue to dip in 1HCY12.
The new FSI rules have increased the developable area by 35%. For example – If the permissible FSI on a land parcel was 1.33 earlier, it will now be 1.8. Similarly FSI for Mumbai suburbs capped at 2.0 will now translate to developable area using FSI of 2.0 X 1.35 = 2.7. This is good news for developers and buyers as well.
Ears on the Ground and site-visits verified availability of discounts up to 5-7% depending on the project. Developers have launched promotions such as absorption of pre-EMI interest till delivery, floor rise waivers, partly furnished apartments to attract customers. Significant discounts are only available to those who are ready to make advance payments. We continue to believe developers will oblige with further discounts (15-25%) as volumes continue to dip in 1HCY12.
The new FSI rules have increased the developable area by 35%. For example – If the permissible FSI on a land parcel was 1.33 earlier, it will now be 1.8. Similarly FSI for Mumbai suburbs capped at 2.0 will now translate to developable area using FSI of 2.0 X 1.35 = 2.7. This is good news for developers and buyers as well.
Sunday, January 15, 2012
Historical Housing Loan Accounts Data
The following Chart Shows the Historical Housing Loan Accounts Data in India. By this we can estimate the top 5 Real Estate Markets in India - Mumbai, Delhi NCR, Bangalore, Chennai and Pune.


Subscribe to:
Posts (Atom)